
You bought Bitcoin years ago, it is worth considerably more now, and you would like to get some use out of that without handing a chunk of it to the IRS. That is the problem. The IRS treats crypto as property, so the moment you sell appreciated coins, you owe capital gains tax on everything above what you paid.
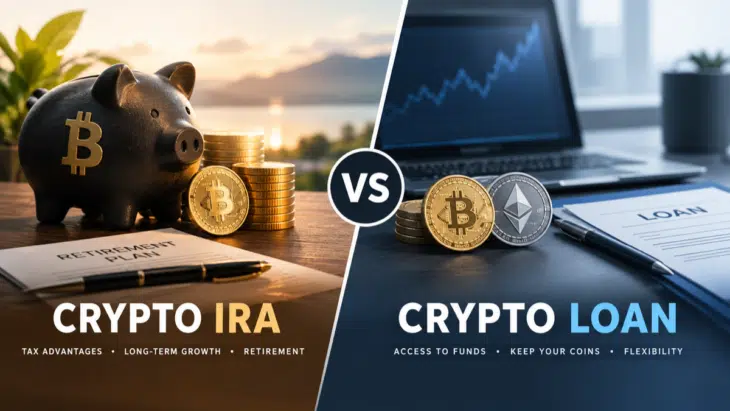
Two products get pitched as the way around this: a crypto-backed loan and a crypto IRA. Both genuinely do avoid a taxable sale, which is why they get mentioned in the same breath. But they are not alternatives to each other, and here is the part that surprises people: for the coins already sitting in your wallet, only one of them is even legally available. That single fact decides most of this.
What Each One Actually Does
A crypto-backed loan is the simpler of the two. You hand over Bitcoin as collateral, the lender gives you cash or stablecoins against it, usually up to about half what your collateral is worth. You keep the upside if the price runs. You get the coins back when you repay. We walk through the mechanics in what is a crypto loan, and current rates sit on our loan comparison page.
A crypto IRA is a retirement account that happens to hold crypto. You open it with a specialized custodian, put cash in, and the custodian buys Bitcoin inside the account on your behalf. After that, it behaves like any other IRA: a Traditional IRA defers the tax until you withdraw in retirement, a Roth lets qualified withdrawals come out untaxed entirely. The tax advantage lives in the account wrapper, not in the Bitcoin.
Cash Now, or Tax-Free Growth Later?
A loan solves a problem you have this month. Money lands in days, sometimes minutes, and nothing gets sold. What it costs you is interest, plus the risk of a margin call if your collateral drops far enough. Ignore that call and the lender sells your coins to cover itself. There is no tax benefit here in the positive sense. You are simply not triggering a sale.
An IRA solves a problem you will have in 30 years, and the word “later” is carrying real weight. Pull money out before you turn 59 and a half and you generally owe a 10% penalty on top of ordinary income tax, with only narrow exceptions. Contributions are capped as well: you can put in $7,500, or $8,600 if you are 50 or older in 2026. This is a slow way to build a position. It is not a way to get cash for something you need in March.
So, a loan is for a need you have now. An IRA is for money you are genuinely willing to lock away for decades.
Why You Cannot Do Both With the Same Coins
Most comparisons skip this, and it is the most useful thing on this page. Two rules in the tax code sit between you and the obvious plan.
- You cannot borrow against crypto held inside an IRA. The IRS treats using an IRA as security for a loan as a prohibited transaction, and you, as the account owner, count as a “disqualified person” under Section 4975. The specific consequence sits in Section 408(e)(4): pledge your IRA as security and the account stops being an IRA, with all its assets treated as distributed to you. This is not a slap on the wrist. Losing IRA status means the whole balance becomes taxable at once, and prohibited transactions separately carry an excise tax that starts at 15% and can climb to 100%. Collateral for a crypto loan has to be coins held outside a retirement account.
- You cannot move Bitcoin you already own into an IRA. Section 408(a)(1) requires IRA contributions to be made in cash. Since the IRS classifies crypto as property, handing over coins does not count as a contribution. You fund the account with dollars and the custodian buys crypto inside it. If you are holding a stack you bought cheap years ago, there is no way to shelter those specific coins in an IRA without selling them first, which triggers exactly the tax bill you were trying to dodge.
Put those two together and the decision largely makes itself. Old coins can be borrowed against but never sheltered. New money can be sheltered but never borrowed against. They are two separate pools of money, not one pool you get to look at two ways.
None of this is tax advice, and if your situation is at all complicated it is worth an hour with a professional. But the structure holds no matter which bracket you are in.
Which One Fits You?
If you:
- Need cash in the next few years: Take the loan. You keep your coins, avoid a sale, and pay interest for the privilege. An IRA cannot help you here, because that money is out of reach without penalty for decades.
- Have a long horizon and new money to contribute: An IRA is worth a serious look for that money. Tax-free compounding over 20 or 30 years is not a small thing, and it costs you nothing extra on coins you were never going to touch anyway.
- Are sitting on a large existing position: An IRA is not available for those particular coins unless you sell them, which defeats the point. A loan is your only route to the value without a taxable sale.
Plenty of people end up doing both—a loan against the old stack, and an IRA funded with fresh cash. The two are not competing for the same dollars.
5 Crypto IRA Providers Worth Knowing
If an IRA makes sense for your new contributions, these are the names worth comparing. We do not receive compensation from any of these companies, so our recommendations are genuine:
- iTrustCapital is our pick for most people. A flat 1% fee on crypto trades, no signup fee, and nothing recurring monthly or annually. Minimums are reported at $1,000 to open and $500 for additional contributions, though neither figure appears on the pricing page itself, so confirm before you fund. It supports 90+ cryptocurrencies plus physical gold and silver across Traditional, Roth, and SEP accounts.
- Unchained already appears on our loan comparison, and its IRA uses the same collaborative multisig custody. For the IRA you hold 2 of the 3 keys yourself, with the custodian holding the third, so no one can move your Bitcoin without you. You pay for that. A $250 annual fee from year two, a 1.5% trading fee, and a $2,000 minimum per transfer or contribution. Bitcoin only. If self-custody is the reason you are in Bitcoin at all, this is the consistent choice.
- Swan Bitcoin runs a Bitcoin-only IRA with Equity Trust as custodian: roughly a 1% trading fee, a small monthly asset fee, and no setup, transfer, rollover, or closure charges. Good fit if you want Bitcoin and nothing else.
- Public.com took over Alto’s CryptoIRA business in a deal announced in November 2025, so if you are reading an older review of “Alto CryptoIRA,” it is describing a product that no longer exists under that name. Alto Trust remains the custodian; the trading experience is now Public’s. Read the fee schedule carefully here, because 2026 customer complaints cluster around fee confusion, an outgoing transfer fee, and steep instant-withdrawal charges.
- Bitcoin IRA is one of the oldest names in the category, but we could not pin down its current fee schedule from public information, and we are not going to guess at numbers that determine what you pay. Ask them directly and get it in writing before you fund anything.
The Cheaper Option Most People Overlook
Before you go shopping for a specialized crypto IRA custodian, know that the cheapest way to hold Bitcoin in a retirement account usually is not a crypto company at all.
An ordinary Traditional or Roth IRA at any mainstream brokerage can buy a spot Bitcoin ETF. IBIT and FBTC both charge a 0.25% expense ratio, well under the 1% to 1.5% per-trade fees that dedicated crypto IRA custodians charge, with no separate custody fee stacked on top. The catch is that you do not own Bitcoin, you own a fund that owns Bitcoin. No self-custody, no withdrawing coins to your own wallet. If all you want is price exposure inside a retirement account, that is a perfectly reasonable trade.
401(k) plans are slowly moving the same direction. An August 2025 executive order told the Department of Labor and SEC to clear regulatory friction around alternative assets in 401(k)s, and the DOL had already withdrawn its earlier warning against crypto in retirement plans.
Some providers, including Fidelity’s Digital Assets Account, let employers offer a Bitcoin sleeve, capped at 20% of contributions when it launched. That cap has not visibly changed, but it is the oldest figure on this page, so check with your plan rather than trusting it blindly.
The regulatory road is open. Whether your specific plan has driven down it is a question for your HR department.
Common Questions People Ask:
Can I use my crypto IRA as collateral for a loan?
No, and the downside is worse than a rejected application. Section 4975 treats it as a prohibited transaction, which can cause your entire IRA to lose its tax-advantaged status, not merely the portion you pledged. Collateral has to come from coins held outside a retirement account.
Can I move Bitcoin I already own into an IRA?
Not directly. Contributions must be made in cash under Section 408(a)(1), so you put dollars in and the custodian buys crypto inside the account. Moving existing coins would mean selling them first, which is the taxable event you were trying to avoid.
Which is better?
Neither, and that is not a dodge. They solve different problems. A loan is for cash you need now against coins you already hold. An IRA is for long-term tax-advantaged growth on new money. Most people who use both are not choosing between them, they are applying each to a different pile of money.
What if I only have a small amount to start?
Account minimums vary a lot, a reported $1,000 at iTrustCapital, up to a confirmed $2,000 per contribution at Unchained. If those are out of reach, a spot Bitcoin ETF inside a regular brokerage IRA has no crypto-specific minimum at all, and costs less in fees besides.
Rates, fees, and minimums change constantly. The rules do not. Check the current numbers before you commit collateral or contributions, and if your tax picture is anything but simple, an hour with a professional will cost less than getting this wrong.
Sources
- IRS: 2026 IRA contribution limits
- IRS: prohibited transactions, including using an IRA as loan security
- 26 U.S.C. 408 and 26 U.S.C. 4975
- IRS: tax on early distributions
- iTrustCapital pricing
- Unchained pricing
- Swan Bitcoin IRA
- Alto: sale of CryptoIRA to Public and Public.com crypto IRA fees
- iShares Bitcoin Trust (IBIT) and Fidelity Wise Origin Bitcoin Fund (FBTC)
- Executive order on alternative assets for 401(k) investors
- DOL Compliance Assistance Release 2025-01
- SHRM: Fidelity’s 401(k) bitcoin option and its 20% cap